Stablecoin yield rule revives crypto vs. banking industry fight
Published in Political News
WASHINGTON — Banking industry representatives came out firing Wednesday after regulators finalized a rule settling the debate over a legal loophole created by Congress in favor of cryptocurrency exchanges’ ability to pay interest on account owners’ stablecoin holdings in certain instances.
Last year’s law known as the “GENIUS Act” created a regulatory framework for stablecoins — digital assets pegged to stable assets like the U.S. dollar or Treasury bills — that are designed to be less volatile than traditional cryptocurrencies like bitcoin.
In a nod to banking industry concerns over the potential loss of deposits to stablecoin accounts, the law barred stablecoin issuers like Circle and Tether from offering interest payments or rewards as an enticement. However, the law left the door open to third-party intermediaries, primarily crypto exchanges, offering yield-bearing options.
The final rule from the Office of the Comptroller of the Currency makes clear that exchanges like Coinbase and Kraken couldn’t offer interest or rewards simply for holding, using or retaining stablecoins for transactions. But other activities involving stablecoins would be eligible on a case-by-case basis, the OCC said, without providing a specific list of allowable use cases.
One potentially eligible activity, according to experts, might be participation in “liquidity pools” offered on platforms like Uniswap, where users deposit two or more stablecoins that can be easily swapped, supporting liquidity and limiting volatile price spikes or declines. In return for contributing to the pool, users receive trading fees and other incentives.
Since such an activity doesn’t fall within the prohibited categories, it’s more likely the OCC wouldn’t flag it for compliance violations under the final rule.
That’s a major, crypto industry-backed shift from the earlier proposed rule, which maintained a general ban on arrangements paying interest or rewards while allowing a “rebuttable presumption” opportunity to explain why an activity would not violate the law.
Within hours of digesting the 721-page rule, the American Bankers Association had seen enough.
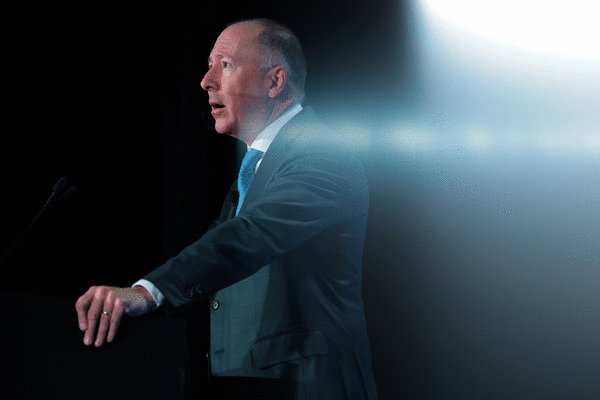
“While the rule includes several positive steps, we disagree with the OCC’s decision to move away from its original position on stablecoin yield,” ABA President and CEO Rob Nichols said in a statement. “The result is a final rule that will preserve the status quo for crypto platforms despite Congress’s clear intent to protect local lending.”
The Blockchain Association recommended that the OCC drop the rebuttable presumption provision, which would have placed the burden of proof on the industry to explain why issuer arrangements with third parties didn’t violate the law’s yield ban. The organization said that provision went beyond what Congress intended and that the final rule more closely aligned with the statutory text.
“We are especially grateful that the OCC listened to the industry,” Blockchain Association chief policy officer Lindsay Fraser said in a statement, adding that the final rule reflects changes the group’s members suggested during the public comment period.
The final rule should make it easier for stablecoin issuers to explain their utility that justifies the yield being indirectly offered, said Steve Gannon, a partner at Davis Wright Tremaine.
“If it’s difficult for an issuer to come up with that description, maybe they shouldn’t be paying yield,” Gannon said.
After passage of the 2025 law, the continuing legal uncertainty over stablecoin yield bled into the debate over the broader crypto industry “market structure” bill that the House passed but stalled in the Senate.
The Senate version aimed to settle the yield debate largely by leaving to regulators the final decisions on what activities might be eligible for incentive payments.
Within a year of enactment, regulators would have to issue a rule defining which “rewards or incentives based on bona fide activities or bona fide transactions that are not economically or functionally equivalent to the payment of interest or yield on an interest-bearing bank deposit” are allowed, the latest bill text says.
The measure also provides examples of permissible activities, such as “providing liquidity for market-making activity,” i.e. liquidity pools.
The bill also contains a “regulatory circuit-breaker” provision, allowing regulators to bar previously-allowed interest or yield payments if community banks — defined as institutions with assets totaling less than $10 billion — have suffered deposit flight resulting in “substantial detrimental impact” to those banks’ deposits.
That so-called kill switch provision might ease some qualms about the legislation, known as the “Clarity Act,” given the final OCC rule that appears to be less restrictive on stablecoin yield, Gannon said.
“Maybe there’s a way to get a skinny Clarity Act in place during a lame-duck session,” he said.
___
©2026 CQ-Roll Call, Inc., All Rights Reserved. Visit cqrollcall.com. Distributed by Tribune Content Agency, LLC.
Comments